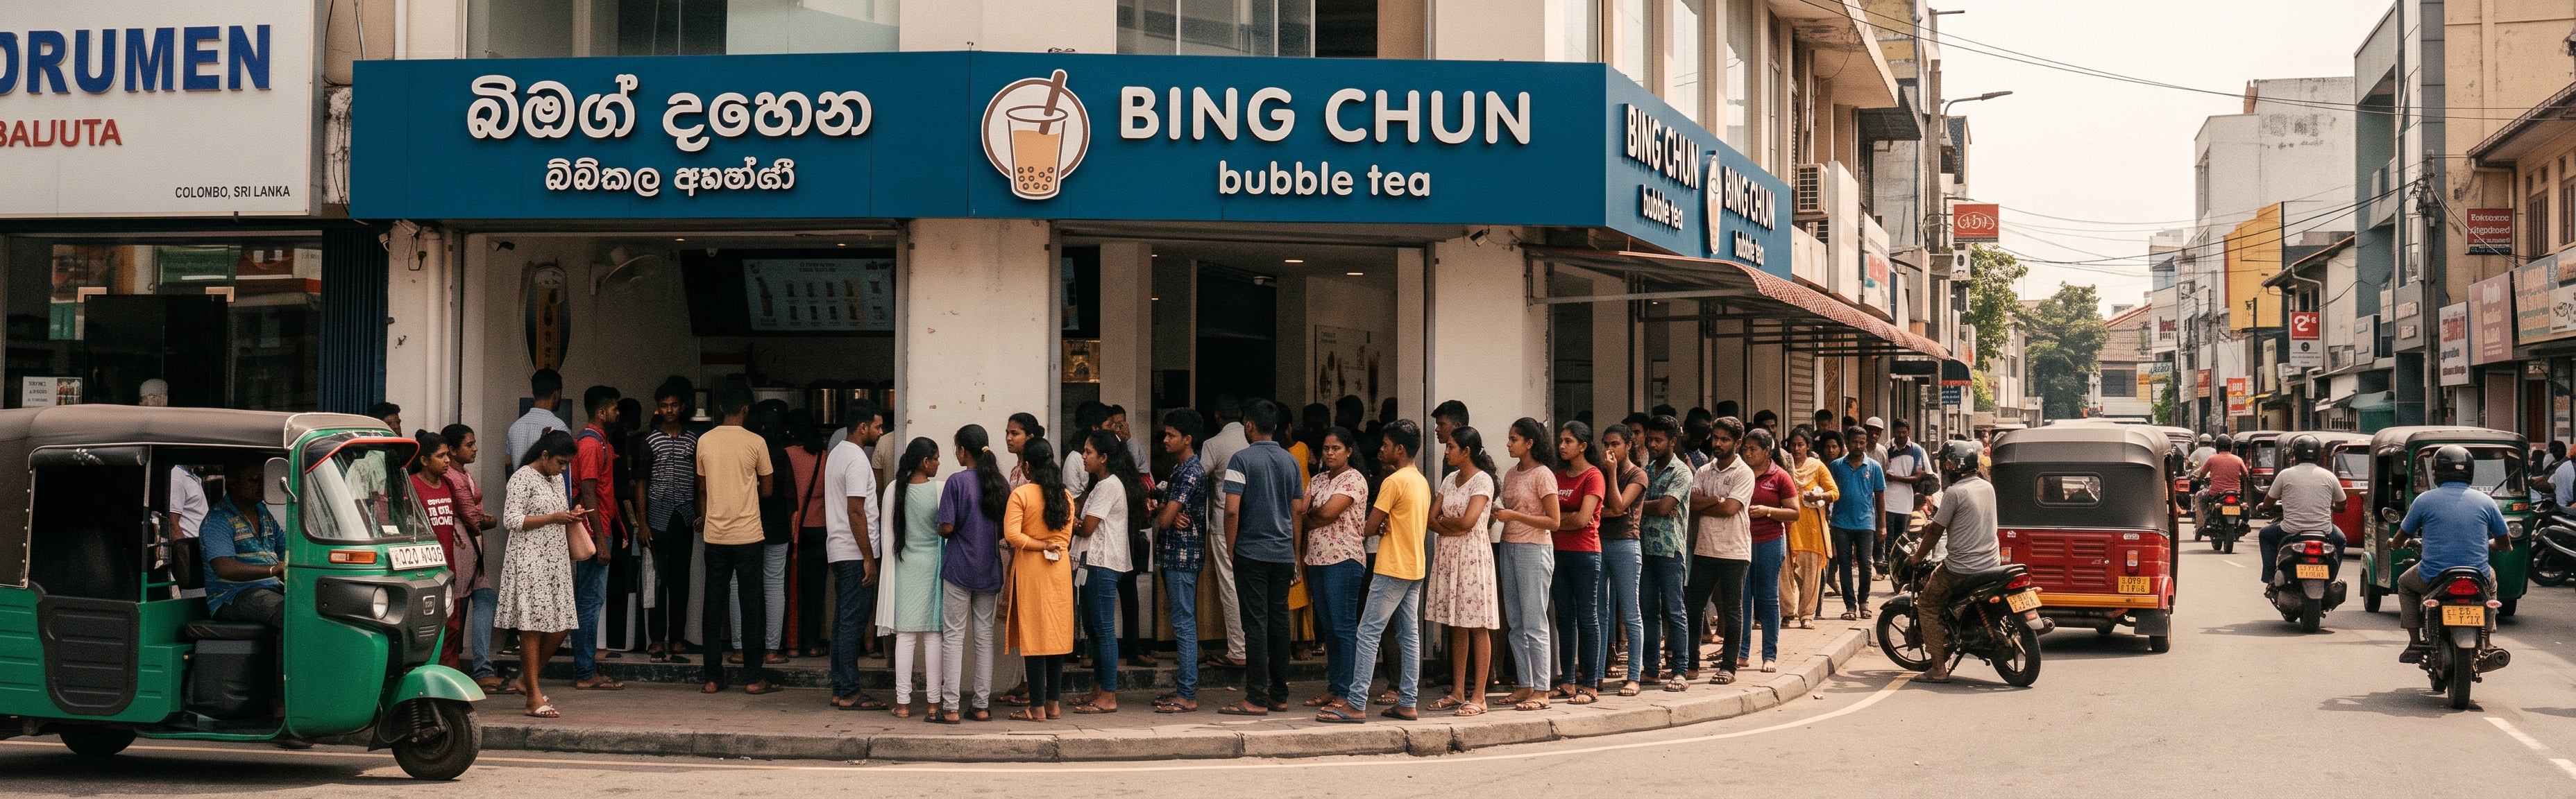
අලෙවිසැල් හැත්තෑනවයයි. දෙකෙන්ම. Barista ශ්රී ලංකාවට එතැනට ළඟා වීමට වසර 15ක් පමණ ගත විය. Bing Chun ට ගත වූයේ මාස 14ක් පමණි.
2025 අප්රේල් හෝ මැයි මාසය පමණ, Kollupitiya, Galle Road එකේ bubble tea සහ soft serve shop එකක් විවෘත විය. කිසිවෙකු එය announce කළේ නැත. press release එකක් හෝ record කළ launch event එකක් නොවීය. පළමු public traces වන්නේ පුද්ගලයන් 50-60ක පමණ queue එකක් LKR 200කට ice cream විකුණන shop එකක් ඉදිරිපිට සිටිනු විස්තර කරන 2025 ජූනි සහ ජූලි මාසවල Instagram posts ය.
2026 ජූනි වන විට, ශ්රී ලංකා ව්යාපාරික මාධ්ය වාර්තා කළේ Pepiliyana LAUGFS supermarket එකක් තුළ Bing Chun ගේ **හැත්තෑනවවන outlet** එක විවෘත වීමයි. එම කාලයේම, outlets 225ක් සහ වසර 123ක ඉතිහාසයක් ඇති Perera and Sons වර්ෂයකට outlets 15-16ක් පමණ එකතු කරමින් සිටියේය. Barista ශ්රී ලංකාව, එහි වඩාත්ම හොඳ වර්ෂයේදී, outlets 32ක් එකතු කළේය.
මෙය දෙවන Scale File එක වන අතර, එය පළමුවැන්නාට mirror image එකකි. Barista පෙන්වූයේ company එකක් architecture එකක් build කර පසුව growth ලබන විට සිදුවන දේයි. Bing Chun පෙන්වන්නේ company එකක් දැනටමත් **finished architecture** එකක් import කර, එය නව රටක switch on කරන විට සිදුවන දේය.
ඔබට product-market fit සහ outlets 4ක් තිබී, මෙම brand එක සෑම දෙවන junction එකකම පෙනී යනු නරඹමින්, එය කෙසේ සිදුවේදැයි විමසමින් සිටී නම්, මෙම case එක ඔබටයි. නමුත් answer එක ඔබ අපේක්ෂා කරන එක නොවේ, වඩාත් වැදගත් question එක වන්නේ ඔවුන් එය කළේ කෙසේද යන්න නොව, එය කරන අතරතුර risk එක දරන්නේ කවුද යන්නය.
ස්වකීය රට කිසිදාක conquer නොකළ company එක
Bing Chun ඇත්තටම කුමක්දැයි එතැනින් ආරම්භ කරමු, මන්ද ශ්රී ලංකාවේ සෑම කෙනෙකුම පාහේ එය වැරදියට තේරුම් ගෙන ඇති බැවිනි.
Bing Chun, හෙවත් 冰淳茶饮, Henan province, Xinxiang හි headquarters ඇති Henan Liangdi Catering Management Co. Ltd සතු tea chain එකකි. පළමු shop එක 2012 විවෘත විය. company එක formally 2017 පිහිටුවන ලදී. 2023 අගෝස්තු වන විට China තුළ stores 2,300ක් ඉක්මවා ගොස් තිබුණි.
ඔබ එය place කරන තෙක් එය දැවැන්ත ලෙස පෙනේ. එකම province එකෙන්ම category leader එක වන Mixue ට stores 45,000කට වඩා ඇත. Bing Chun යනු Chinese national champion එකක් නොවේ. එය **ස්වකීය home market එකවත් කිසිදාක ජයගත් provincial operator** කි. industry data platform 窄门餐眼 අනුව, වසර 14කට පසුවත් එහි stores වලින් අඩකට වඩා තවමත් Henan තුළ concentrated ව ඇති අතර, roughly 72%ක් cities වලට වඩා townships වල පිහිටා ඇත.
company එකේම English-language website එක කියවන්න, එය ශ්රී ලාංකික reader කෙනෙකු literally ගැනීමට කිසිසේත් සිතාවත් නොසිටින language එකකින්, එය ඇත්තටම කුමක්දැයි එය ඔබට කියයි. එහි stated vision එක වන්නේ **world's most valuable investment tea brand** එක බවට පත් වීමයි. එහි stated culture එක වන්නේ small towns වල තරුණයන්ට ඔවුන්ගේ entrepreneurial dreams සාක්ෂාත් කර ගැනීමට උදව් කිරීමයි. එහි internal service centres අටෙන්, Supply Chain Centre එකක් සහ **Investment Management Centre** එකක් ඇතුළත් වේ.
මෙය Bing Chun ට පමණක් අනන්ය දෙයක් නොවේ. එය සමස්ත Chinese tea export wave එකේම structure එකයි, එය numbers disclose කිරීමට සිදු වූ එකම තැනෙහි document කර ඇත. Mixue list වූ විට, එහි prospectus එකෙන් පෙන්නුම් කළේ franchise fees ලෙස revenue වලින් roughly **2.4%**ක් ලැබී ඇති බවයි. approximately **97.6%**ක් එහිම franchisees වෙත ingredients, equipment සහ packaging විකිණීමෙන් ලැබී ඇත. Guming goods සහ equipment sales වලින් 79.5%ක් වාර්තා කළේය. Cha Bai Dao 94.8%ක් වාර්තා කළේය.
Shenzhen venture fund RF Capital හි Ray Hsu එය CKGSB වෙත එක වාක්යකින් පැවසුවේය: tea සහ ice cream brand එකකට වඩා, Mixue essentially supply-chain machine එකකි.
Bing Chun එහි revenue split publish නොකරයි. එය listed නොවන අතර audited public accounts කිසිවක් file නොකරයි. නමුත් එය core products සඳහා self-built factory එකක්, dedicated Supply Chain Centre එකක්, සහ Investment Management Centre එකක් run කරන අතර, equipment line එක franchise fee එකට වඩා roughly 6 ගුණයක් වන franchise package එකක් විකුණයි. architecture එක කියවීමට prospectus එක අවශ්ය නැත.
2025 අවසානය වන විට group එක ලොව පුරා **signed** stores 4,000කට වඩා වාර්තා කළ අතර, ඉන් 1,000කට වඩා countries 20ක් හරහා overseas විය. 2026 ජූලි වන විට එය signed 4,500කට වඩා, roughly 1,500ක් overseas සමඟ වාර්තා කළේය. එහි පළමු foreign markets Vietnam සහ Laos 2019 වූ අතර, පසුව Indonesia, Thailand සහ Malaysia.
ඔවුන් අප out-execute කළේ නැත. Execution දැනටමත් finish වී තිබුණි.
ශ්රී ලාංකික owner කෙනෙකු sit with කළ යුතු කොටස මෙයයි. Bing Chun local operators out-execute කළේ නැත. එය execution complete කරගෙන, වසර 14ක් සහ Chinese stores 2,300ක් සඳහා paid for කරගෙන පැමිණි අතර, ශ්රී ලාංකික වර්ෂය gත කළේ construction වෙනුවට distribution කිරීමෙනි.
container එක landed වූ විට already finished වී තිබූ දේ බලන්න.
**shop එක square metres 12කි.** එය China තුළ company එකේ published minimum net usable area එකයි, minimum storefront sign height මීටර් 2.4ක් සමඟින්, minimum door width සහ interior depth මීටර් 2ක්, සහ 380V three-phase power amps 100ක් හෝ ඊට වැඩි requirement එකකි. Square metres 12ක් café එකක් නොවේ. එය person කෙනෙකු සිටින serving position එකකි. එය lease universe එක, fit-out cost එක, staffing model එක සහ payback maths එක එකවර වෙනස් කරයි, සහ traditional ශ්රී ලාංකික F&B operator කිසිවෙකු viable ලෙස consider නොකරන locations විවෘත කරයි.
මෙරට බොහෝ owners photograph වීමට proud වන shop එකක් design කරයි. Bing Chun සැලසුම් කළේ 80 වතාවක් open කළ හැකි unit එකකි.
**labour එක ලෙසින්ම deliberately deskilled ය.** Bing Chun ශ්රී ලංකාවේම careers page එකෙන් advertise කරන්නේ අවුරුදු 18-30, friendly සහ team-oriented, experience අවශ්ය නොවේ, training ලබා දෙන බැවිනි. outlets අතර travel කරමින් standards maintain කරන Junior Trainer role එකක්, සහ island-wide fit-outs run කරන Renovation Supervisor role එකක් තිබේ. head office Colombo 03 හි ය. applications WhatsApp හරහාය.
එය low-quality hiring policy එකක් නොවේ. එය design decision එකකි, සහ එය outlet 50 possible කරන එකයි. ඔබේ operation talent require කරන්නේ නම්, ඔබට ඒවා 80ක් open කළ නොහැක, මන්ද leases scale වන rate එකට talent scale නොවන බැවිනි.
**menu එක variety එකක් නොව permutation එකකි.** ශ්රී ලාංකික menu එක රුපියල් 200 soft serve එකේ සිට රුපියල් 650 premium fruit teas දක්වා, 3 ගුණයකට වඩා spread එකක් සමඟ පවතී. නමුත් cups තුළ ඇත්තටම ඇති දේ බලන්න. tea bases, syrups, powders, dairy substitutes සහ toppings කුඩා set එකකින් recombine කර build කරන ලද bubble teas, milk teas, fruit teas, milkshakes, sundaes සහ ice creams. එම menu එකේ, වෙනත් දෙයක් සඳහා store එකේ දැනටමත් නොමැති raw material එකක් require කරන්නේ almost කිසිවක් නැත.
**fit-out එක negotiation එකක් නොව internal process එකකි.** ස්වකීය Renovation Supervisor employ කරන company එකක් site එකින් එක tender කරන්නේ නැත. එය repeatable build එකක් run කරයි. outlet 79 outlet 9 වගේ පෙනෙන්නේ ඒ නිසාය, සහ lease එකක් sign කිරීම සහ door එකක් open කිරීම අතර gap එක weeks වලින් measure වන්නේ ඒ නිසාය.
**franchise terms structured කර ඇත්තේ franchisor එකට opening day එකේම paid වීමටයි.** China තුළ, published package එක roughly yuan 130,000ක් වන අතර, yuan 99,800ට promote කරනු ලැබේ. එහි ඇතුළත්: townships වල yuan 6,800 සිට cities වල yuan 16,800 දක්වා tiered franchise fee එකක්, refundable yuan 10,000 deposit එකක්, equipment yuan 60,000ක් පමණ, initial materials yuan 23,000ක් පමණ, සහ fit-out yuan 20,000-30,000ක්.
franchise listing sites publish කරන Thailand package එක roughly baht 845,000ට run වන අතර, ඉන් annual franchise fee එක baht 50,000ක් වන අතර equipment එකම baht 450,000ක් වන අතර, ඊට උඩින් first ingredients baht 200,000ක් ඇත.
market දෙකෙහිම franchise fee එක trivial ය, hardware සහ inventory එකයි ව්යාපාරය. එය Mixue ගේ 97.6% structure එක prospectus එකකට වඩා invoice line items තුළ visible වීමයි.
එබැවින් Bing Chun store එකක් Kurunegala හි open වන විට, වැදගත් question එක අසන්න. එදින ලාභ ලබා ඇත්තේ කවුරුන්ද?
මිනිසුන් නැවත එන්නේ ඇයි, සහ එහි හේතුව සතු කවුරුන්ද
Bing Chun ට app එකක්, loyalty card එකක්, points programme එකක් හෝ customer database එකක් නැත. outlets 79ක සිටින විටත්. 2026 දී.
obvious reading එක වන්නේ මෙය ඔවුන් තවමත් නොසපයන gap එකකැයි යන්නයි. obvious reading එක wrong ය, එය ඇයි දැයි තේරුම් ගැනීම මෙම case study එකේ වඩාත්ම valuable දෙයයි.
**රුපියල් 200 soft serve එකෙන් ආරම්භ කරන්න.** රුපියල් 200 යනු ශ්රී ලාංකික consumer කෙනෙකු deliberate වන threshold එකට පහළින් වේ. ජයගත යුතු consideration phase එකක් නැත, endure විය යුතු comparison එකක් නැත, ඒ ගැන සිතීමට හේතුවක් නැත. එය cheap product එකක් නොවේ. එය menu item එකක් ලෙස book කරන ලද acquisition cost එකකි.
**ඉන්පසු queue එක.** Bing Chun ගේ opening posts සෑම විටම same mechanic එකකින්ම run වේ: opening day beverage purchase ඕනෑම එකක් සමඟ free ice cream. පළමු දිනයේ queue එක deliberately, giveaway margin එකේ cost එකෙන් bought වේ. queue එකක් යනු company එකකට buy කිරීමට buy කිරීමට අවශ්ය නොවන creative asset එකකි. beverage counter එකක් කිසිවෙකු film කරන්නේ නැත. පුද්ගලයන් 50ක් එයින් පිටත සිටින විට සියලුම දෙනා film කරයි.
Instagram, Facebook, X සහ YouTube හරහා Bing Chun ගැන ශ්රී ලාංකික social posts සහ comments sample එකක, queue සහ social experience 2025 ජූනි සිට 2026 දක්වා run වූ single largest category එක විය. company එකේ largest marketing asset එක මිනිසුන් පේළියක් වන අතර, එයට එය pay නොකරයි.
**ඉන්පසු almost කිසිවෙකු notice නොකරන කොටස.** Sinhala භාෂාවෙන් post කරන, individual outlets විසින් run කරන outlet-level social accounts ඇත. එක Negombo account එකක් 🚨 මීගමුව, අපි OPEN යනුවෙන් එහිම opening එක announce කළේය. franchisee එක, local language එකෙන්, තමන්ගේම cost එකෙන් content produce කරයි.
එකම content එකෙන් jobs දෙකක් sidha වේ. scroll කරන customer කෙනෙකුට පෙනෙන්නේ drink එකකි. scroll කරන prospective investor කෙනෙකුට පෙනෙන්නේ consultant කෙනෙකුට pay කිරීමකින් තොරව ලබාගත් demand validation එකක් වන 50-person queue එකකි. content spend එකක්, conversions දෙකක්. consumer funnel එකත් franchise recruitment funnel එකත් එකම funnel එකයි.
criticism එකද එයට feed කරයි. ශ්රී ලාංකික commenters drinks rubbish ය, queue එක absurd ය, price එකින් quality පිළිබිඹු වේ යැයි පවසා ඇත. රුපියල් 200කට, quality criticism trial එකට deter නොකරයි. සෑම complaint එකක්ම brand name එකත් price point එකත් නව audience කෙනෙකු වෙත රැගෙන යයි.
cup එක තුළ ඇත්තටම සිදුවන දේ
මෙම drinks වලින් එකක් finish කරන කෙනෙකු watch කරන්න. ඔවුන් cup එක down කරන්නේ නැත. ඔවුන් එය work කරමින්ම සිටින්නේ, melted ice sipping කරමින්, යමක් chase කරමින්. එය enjoyment එකක් නොවේ. එය withdraw වූ reward එකක් pursue කරන person කෙනෙකි.
**Cold එක dose එක hide කරයි.** sweet taste perception එක temperature dependent වන අතර low temperature එකකදී suppress වේ. ice cold ලෙස consume කිරීමට engineer කරන ලද beverage එකකට, ඒ නිසා room temperature එකකදී outright reject වන sugar load එකක් carry කළ හැක. palate එක කිසිදාක dose එක excessive ලෙස register නොකරයි.
**supply run out වන විට reward curve එක rise වේ.** ice melt වී cup එක hand එකේ warm වන විට, actual concentration dilution තුළින් fall වුවත් perceived sweetness increase වේ. cup එකේ last third එක first එකට වඩා sweet ලෙස taste වේ. pull එක strongest වන්නේ ඉතිරි ඇත්තේ least ප්රමාණයේදීමය.
**peak එකත් end එකත් එකම moment එකයි.** Tapioca pearls sink වේ. final mouthfuls මුළු serving එකේම highest concentration of chew and sugar carry කරයි. පුද්ගලයන් experience එකක් memory කරන්නේ එහි most intense moment එකෙන් සහ final moment එකෙන් වන අතර, මෙම cup එක ඒවා coincide වීමට arrange කරයි. encode වන memory එක average experience එකට justify වන ප්රමාණයට වඩා better ය.
**ඔබ ආහාර ගත් බව කිසිවක් signal නොකරයි.** liquid calories satiety regulation එකට එරෙහිව poorly register වේ. stomach එක satisfied විය හැකි අතර reward system එක satisfied නොවිය හැකිය. ඒවා systems දෙකකි, සහ මෙම product එක එකකට address කර අනෙක ignore කරයි.
**සහ want එක timer එකකින් arrive වේ.** high glycaemic load එකකින්, drink එකේ memory එකක් ලෙස නොව physical wanting එකක් ලෙස subjectively present වන minutes 45-90ක් පසුව trough එකක් produce වේ. commercially matter වන එකම question එක raise වන්නේ එබැවිනි. එය land වන විට customer standing ඇත්තේ කොහෙද?
product එක property strategy එකට meet වන්නේ මෙතැනදීය. China තුළ Bing Chun ගේ published territorial guidance එකෙන් franchisees ගෙන් අසන්නේ existing store එකකින් straight line එකකින් අවම වශයෙන් **මීටර් 300ක්** හරි new stores site කරන ලෙසයි. මීටර් 300. franchisee ඕනෑම කෙනෙකු එය cannibalisation ලෙස හඳුන්වනු ඇත, supply-chain frame එකකදී එය plainly එසේය, franchisor pay වන්නේ unit profit එකකට වඩා unit supplied එකකට වන බැවිනි.
නමුත් එය behaviourally කියවන්න, එය සම්පූර්ණයෙන්ම වෙනස් දෙයකි. මීටර් 300 spacing එකෙන් අදහස් වන්නේ craving එක conditioned cue field එකක් තුළ arrive වීමයි. trough එක land වේ, customer look up කරයි, storefront එකක් එහි ඇත, physiological vulnerability එකේ precise moment එකේදී social proof deliver කරන queue එකක් සමඟින්.
එය missing app එකේ obvious reading එක correct කරයි. Bing Chun customer retention skip කළේ නැත. එය product එකේ return build කර store estate එකේ reminder build කර, software එක unnecessary කළේය. ඔවුන් retention build කළේ නැත. ඔවුන් **recurrence** build කළේය, recurrence එකට monthly cost කිසිවක් නොමැති බැවින් එය run කිරීමට cheaper ය.
එය company එක කර ඇති most sophisticated දෙයයි, sneer කිරීමට වඩා plainly පවසනු ලැබීමට එය deserve වේ.
එය exposure එක sit වන තැනද වේ. relationship එකක් owned වේ. craving එකක් නොවේ. මෙහි habit එක attach වන්නේ sugar, cold, price සහ proximity වෙතටයි, එම හතරෙන් සෑම එකක්ම shipping container එකක් සහ lease එකක් ඇති ඕනෑම කෙනෙකු replicate කළ හැක. franchisee එක competitor කෙනෙකුට next shop එක ගැනීමෙන් occupy කළ හැකි cue field එකක position එකක් purchase කර ඇත.
ශ්රී ලංකාවේ කිසිවෙකු කරන්නේ නැති case එක
මෙය තුළ දෙවන case study එකක් ඇත, සහ ශ්රී ලාංකික business owner කෙනෙකුට එය දෙකෙන් වඩාත් වැදගත් එකයි.
ශ්රී ලංකාවට **franchise statute එකක්, franchise registry එකක්, franchising remit එකේ ඇති regulator එකක්, සහ කිසිදු ආකාරයක statutory pre-contract disclosure obligation එකක් නැත.** Franchise agreements ordinary commercial contracts වන අතර contract law එකෙන් සහ Intellectual Property Act No. 36 of 2003 එකෙන් govern වේ.
දැන් compare කරන්න. Malaysia ගේ Franchise Act 1998 යටතේ, foreign franchisor කෙනෙකු franchise එක register කළ යුතු අතර, රටේ franchises විකිණීමට Section 54 යටතේ separate approval එකක් ලබා ගත යුතුය, sign කිරීමට අවම වශයෙන් දින 10කට පෙර prospective franchisee කෙනෙකුට **audited accounts වසර 3ක්** ඇතුළත් prescribed disclosure document එකක් hand කළ යුතුය. එසේ නොකිරීම criminal offence එකකි. Indonesia Government Regulation No. 42 of 2007 යටතේ Ministry of Trade එක සමඟ registration එකක් සහ financial information පිළිබඳ pre-contract disclosure එකක් require කරයි.
මෙය Bing Chun එකට හෝ එහි franchises විකුණන ඕනෑම කෙනෙකුට එරෙහි accusation එකක් නොවේ. ඔවුන් ශ්රී ලාංකික law එකට fully comply වේ, ශ්රී ලාංකික law එක කිසිවක් නොඅසන බැවිනි. එය මෙම article එකේ සෑම reader කෙනෙකුම operate වන market එක පිළිබඳ observation එකකි, ශ්රී ලාංකික operating entity එකක්, director list එකක්, හෝ published franchise term එකක් අපට සොයාගත නොහැකි වූයේ ඇයිදැයි එය explain කරයි. ඒවායින් කිසිවක් exist වීමට කිසිවක් require නොකරයි.
එබැවින් state එක නොකරන work එක ශ්රී ලාංකික franchisee කරගත යුතුය. එහි අර්ථය sales conversation එක ඔබ වෙනුවෙන් නොකරන arithmetic එක කිරීමයි.
Bing Chun ගේ parent company prospective franchisees ට කියන්නේ raw material cost එක **35% ඇතුළත** පවත්වා ගෙන යන බවයි. එම figure එක Chinese domestic input prices මත calculate කර ඇත. එය journey එකෙන් survive නොවේ.
ඉන්පසු ශ්රී ලාංකික import taxation එක compound වේ. Flavoured beverage preparations වලට customs import duty roughly 20%ක්, PAL roughly 10%ක්, CESS 45% දක්වා හෝ specific per-litre rate එකක්, SSCL 2.5%ක් සහ VAT 18%ක් carry කළ හැක, එක් එක් layer cumulative base එකක් මතට layer වේ. Powdered beverage bases, non-dairy creamers සහ tapioca pearls සාමාන්යයෙන් 10-20% duty band එකකට වැටෙන අතර එම para-tariff stack එකම ඊට උඩින් ඇත. Commercial food service equipment ඉතිරි duty එකට පෙර roughly 10-15%ක් duty එකකට වැටේ.
ඉන්පසු currency එක. Rupiya 2025 ජනවාරි dollar එකට roughly 295සිට 2026 අගෝස්තු වන විට roughly 333 දක්වා, සහ yuan එකට roughly 40.2 සිට roughly 44.5 දක්වා move විය. එය මෙම network එක build වූ window එකේම 11-13% depreciation එකකි. imported cost base එක shelf price රුපියල් 200කම පවතින අතරතුර, rupee terms වලින් එයම ප්රමාණයෙන් rise විය.
එය ඔබම model කරන්න. square metres 20ක outlet එකක් ගන්න. Colombo secondary frontage එකක rupees 200ක්/sq ft rate එකකදී rent එක roughly rupees 45,000-65,000ක් වන අතර, sq ft එකට rupees 300-500ක prime Galle Road frontage එකක rent එක rupees 65,000-160,000ක් වේ. staff 4ක් rupees 35,000ට rupees 140,000ක්, EPF සහ ETF employer contributions වශයෙන් 15%ක්, ඊට තවත් rupees 21,000ක්. hours 14ක් සඳහා soft serve machines සහ freezers run කරන three-phase power සඳහා utilities එකතු කරන්න.
cup එකක් sale වීමට පෙර, එය මාසයකට roughly rupees 290,000-430,000ක fixed cost එකකි.
රුපියල් 350ක average ticket එකකදී සහ franchisor ගේ claimed 35% material cost එකකදී, contribution එක cup එකකට roughly rupees 227ක් වන අතර, fixed cost එකේ breakeven එක දිනකට roughly **cups 45-65ක්** වේ. Comfortable ය. sales conversation එක run වන number එක එයයි.
දැන් ශ්රී ලාංකික landed reality එකට correct කරන්න. tariff stack එකෙන් සහ currency move එකෙන් effective cost of goods 55-60%ට push වුවහොත්, contribution එක rupees 140-158ට fall වන අතර, breakeven එක දිනකට **cups 75-100කට** rise වේ. equipment invoice එකට, fit-out එකට, ශ්රී ලාංකික commercial landlords සාමාන්යයෙන් require කරන advance rental මාස 3-6ට, හෝ owner කෙනෙකු තමන් වෙනුවෙන් කිසිවක් take කිරීමට රුපියලක් යාමට පෙරය.
queue වන Colombo site එකකදී cups 100ක් achievable ය. same equipment invoice එකම carry කරමින්, ඒ footfall එකෙන් fraction එකක් ඇති site එකකදී එය materially different proposition එකකි. මීටර් 300 siting rule එකක් යටතේ, පසුව sign කරන franchisees ලාභයට thinner sites ලැබේ.
pillars පහ හරහා Bing Chun
ඉහත සියල්ල narrative ය. ඔබට act කළ හැකි කොටස මෙයයි. Elara හිදී අපි company එකක් pillars පහක් හරහා assess කරමු. ඒවා checklist එකක් නොවේ. ඒවා load-bearing ය, අනෙක් ඒවා කොතරම් strong වුවත් weakest වන ඕනෑම එකක් හරහා business එකක් collapse වේ.
Bing Chun instructive වන්නේ එය pillars තුනක close to perfect වන, එකකින් deliberately absent වන, සහ එහි entire risk එක පස්වන එකේ carry කරන බැවිනි.
Financial Structuring
franchisor එකට, මෙය close to flawless ය. Growth entirely franchisee capital එකෙන් fund කර ඇත. equipment invoice එක, fit-out එක සහ first inventory order එක, single customer කෙනෙකු serve වීමට පෙර, door එක open වන දිනයේම franchisor ගේ return එක settle කරයි. bad site එකකට, bad operator කෙනෙකුට හෝ bad year එකකට balance sheet exposure එකක් නැත.
franchisee එකට, same structure එකම very differently reads වේ. sovereign debt එකේ default වූ, reserves tighten වූ විට imports previously restrict කළ රටක, dollar සහ yuan-denominated cost base එකකට එරෙහිව rupee-denominated revenue line එකක් sit වේ. franchisee එක currency risk එක, tariff risk එක, site risk එක සහ novelty risk එක carry කරයි. franchisor එක shipping එක carry කරයි.
Barista ශ්රී ලංකාව structurally similar දෙයක් කර different result එකක් ලබා ගත්තේය, එය තේරුම් ගැනීමට worth ය. එයද capital expenditure franchisees වෙත push කළේය. නමුත් එය market එකේ brand එක operate කරමින් වසර 15කට පසුව, published payback expectations සමඟ, සහ franchisee profitability එකට accountable එහිම area management එක සමඟ එසේ කළේය. structure එක problem එක නොවේ. sequencing එකයි accountability එකයි.
People and Culture
Strong ය, deliberately එසේය. අවුරුදු 18-30, experience අවශ්ය නොවේ, in-house training ලබා දේ, estate එක පුරා standards maintain කරන එක travelling Junior Trainer කෙනෙක්. operating model එකේ කිසිවක් skilled individual කෙනෙකු මත depend නොවේ, එය හරියටම model එක වර්ෂයකින් 80 වතාවක් replicate කළ හැකි හේතුවයි.
මෙම article එකේ readers බහුතරයට uncomfortable mirror එක වන්නේ ඔවුන්ගේ business එක opposite way එකින් build කර ඇති බවයි. එය replace කළ නොහැකි පුද්ගලයන් එක් දෙදෙනෙකු මත depend වේ, සහ ඔබ එය quality ලෙස call කරයි. එය quality නොවේ. එය ceiling එකකි.
model එක thin වන්නේ store level එකට ඉහළිනි. franchised ඒවා ඇතුළුව සෑම store එකකම area coach කෙනෙකු place කරන, එම franchisee ගේ revenue එකට සහ profit එකට personally accountable Barista සමඟ compare කරන්න. එයට equivalent structure එකක්, named ශ්රී ලාංකික operating company එකක්, හෝ head office address එකක් සහ WhatsApp number එකකට වඩා publicly identifiable local management එකක් අපට සොයාගත නොහැකි විය.
Operational Excellence
ශ්රී ලාංකික owners hardest study කළ යුත්තේ මෙම pillar එකයි, එය free to copy වන එකයි.
square metres 12ක minimum footprint එකක්. per-site negotiation එකකට වඩා fit-out එක repeatable internal process එකක් බවට හරවන in-house Renovation Supervisor කෙනෙක්. bases, syrups සහ toppings shared small set එකකින් build කර ඇති items 30කට වඩා menu එකක්. සෑම outlet එකකම standard opening hours, උදේ 9 සිට රාත්රී 11 දක්වා. shift එකේ සිටින්නේ කවුරුන්ද යන්න මත output vary නොවන ලෙස pre-portioned inputs භාවිතා කරමින් standardised preparation.
consistency එක downstream fail කළ නොහැකි ලෙස upstream engineer කර ඇත. එය owner කෙනෙකු unannounced walk in වීමෙන් consistency engineer කරන ශ්රී ලාංකික default එකට opposite ය.
Technology Injection
almost කිසිවක් නැත, එය gap එකකට වඩා finding එකකි. app එකක් නැත, loyalty programme එකක් නැත, customer relationship management එකක් නැත, owned customer data එකක් නැත. Franchise recruitment සහ job applications දෙකම WhatsApp හරහා run වේ.
මෙම series එකේ episode එකකින් Barista work නොකළ unit economics මතට 2007 දී enterprise platform එකක් install කරමින්, තවත් decade එකකට ලාභය faster සහ better-documented ලෙස ලබා ගැනීම පෙන්නුවා. Technology එය යටින් sit වන ඕනෑම දෙයක් amplify කරයි.
Bing Chun එම mistake එක කළේ නැත. එය වඩාත් interesting දෙයක් කළේය. එය retention job එක product එකට සහ store estate එකට relocate කර, technology එක unnecessary කළේය. pillar 4 මෙතැන missing නොවේ. එය substitute කර ඇත.
එම choice එකේ cost එක වන්නේ company එකට customer data එකක්, direct channel එකක් හෝ queue thin වන විට activate කළ හැකි relationship එකක් නොමැති බවයි. එයට recurrence ඇත, එය defend කිරීමට way එකක් නැත.
Demand and Revenue Engine
වඩාත්ම impressive pillar එකත් වඩාත්ම fragile එකත්. deliberation threshold එකට පහළින් entry price එකක්, free content generate කරන manufactured queue එකක්, local languages වලින් franchisee-funded local marketing එකක්, approval එකකට වඩා return එකකට engineer කරන ලද product එකක්, reminder deliver කිරීමට spaced store estate එකක්.
මෙම engine එක produce නොකරන දේ note කරන්න. එය identical price එකකදී doors දෙකක් යටින් identical product එකකට වඩා Bing Chun preferring reason එකක් produce නොකරයි. Demand එක price, novelty, proximity සහ physiological pull මතට rest වන අතර, ඒවා හතරෙන් කිසිවක් proprietary නොවේ.
leading indicator එකක් already record එකේ ඇත. 2025 ජූනි මාසයේදී, Kollupitiya outlet එක open වීමෙන් මාසයක් හෝ දෙකකට පසුව, ශ්රී ලාංකික user කෙනෙකු post කළේ, ඔහු සෑම විටම 50-60ක queue එකකින් දුටු shop එක, එදින, empty බවයි.
Deployment compounding නොවේ
Deployment units open කිරීමයි. Compounding pay back වී next unit fund කරන units ය. ඒවා approximately years 2ක් outside සිට identical ලෙස පෙනේ, ඉන්පසු ඒවා එසේ නොපෙනේ.
Barista ශ්රී ලංකාව outlets 79ට ළඟා වීමට roughly years 15ක් spend කළේය, එම curve එකේ shape එක endpoint එකට වඩා matter වේ. එය years 16ක් outlets 7-8ක sat වූ අතර, 2018 සිට එහි architecture rebuild කර, එවිටින් පසුව accelerate වී, 2025 එකේම outlets 32ක් add කළේය. slow years wasted years නොවීය. ඒවා runway එකයි.
මෙම case study එකේ කිසිවක් Bing Chun architecture bad යැයි කියන්නේ නැත. එය superb ය, ශ්රී ලාංකික owners memory වලින් draw කළ හැකි තෙක් square metres 12 format එක, permutation menu එක සහ deskilled role එක study කළ යුතුය. ඒවායින් සෑම එකක්ම ඔබට available ය, ඒවායින් කිසිවක් foreign capital require නොකරයි.
මෙම case study එක කියන්නේ narrower සහ harder දෙයකි. architecture එක Xinxiang ට අයිතිය. lease එක, equipment loan එක, currency exposure එක සහ staff contracts Kurunegala ට අයිතිය. disclosure regime එකක් නොමැති රටක, එම difference එක understand කරන party එක equipment විකුණන party එකයි.
coming specific test එකක්ද ඇත. queue formation එක 2027 හරහා hold වී, loyalty mechanism කිසිවක් නොමැතිව outlet-level traffic sustain වුවහොත්, ownership එකකින් තොර recurrence එකකැයි අපගේ reading එක revisit කිරීමට අවශ්ය වනු ඇත. highest-density clusters වලින් traffic පළමුව decay වුවහොත්, cue field reading එක confirm වේ. either way answer එක months 12ක් තුළ arrive වන අතර, filing එකකට වඩා street එකේ visible වනු ඇත.
අප ඔවුන්ට දෙන idea එක
Bing Chun ගේ entire ශ්රී ලාංකික cost base imported ය. Sichuan lemons, Fujian tea, Chinese equipment, Chinese packaging, tea, dairy, coconut සහ tropical fruit export quality වලින් grow කර functioning food processing base එකක් ඇති island එකක, hardening currencies වලින් purchase කර rupees වලට sell කර ඇත.
obvious move එක, අප publicly සහ charge එකකින් තොරව offer කරන්නේ, ශ්රී ලංකාව demand market එකක් ලෙස treat කිරීම නවතා South Asia සඳහා sourcing සහ blending hub එක ලෙස treat කිරීම ආරම්භ කිරීමයි. tea base එක, dairy එක සහ fruit එක localise කරන්න. operation එකේ single largest structural risk එක, shipping container එකක් ඇති competitor කෙනෙකුට replicate කළ නොහැකි එකම advantage එක බවට convert කරන්න.
එම idea එක මෙම article එක write කිරීමට අපට cost වන ප්රමාණයට වඩා ඔවුන්ට worth ය, එය owned වීමට වඩා built වීමට අප කැමතියි.